

What buyers actually evaluate in a DFW deal, how to tell real operational help from a rushed sale, and where founders can start today.
Most Dallas–Fort Worth founders don’t wake up one day and decide to sell. It’s more like a thought that shows up early and comes back more often over the years, usually without a clear next step attached to it.
Here’s a reason to take that thought seriously sooner rather than later: local deal activity is picking up. D CEO’s Mergers & Acquisitions Awards this May recognized a Fort Worth disaster-restoration company’s acquisition by a Dallas private equity firm and a Dallas construction business’s move to full employee ownership—real North Texas deals, in the $25–200 million range, which is exactly the size of business most DFW founders are actually running.
That’s worth knowing now, whether a sale is two years out or ten, because the founders who prepare early tend to end up with meaningfully better outcomes than the ones who start thinking about readiness only after a buyer calls.
Plenty of DFW businesses are profitable and growing. Federal Reserve small business survey data shows employer firms reporting steady revenue growth even as their confidence in future performance slips, and that gap between performing well today and continuing to perform once the founder steps back is exactly what a buyer’s diligence team goes looking for.
There is an old line worth remembering here: the best time to fix the roof is before it rains. A business can be profitable without being transferable, and most founders don’t find out which one they built until someone else’s accountants start asking questions.
Transferability comes down to whether the business keeps performing once new ownership takes over: whether the systems, the customer relationships, and the financials all hold up without the founder standing behind them.
That is the real starting point of exit planning for Dallas–Fort Worth business owners. An exit readiness assessment done early, on the founder’s own schedule, surfaces these gaps while there is still time to close them.
For DFW manufacturers and other lower-middle-market operators, that usually means untangling owner dependence, tightening up financial reporting, and documenting the processes that currently live only in someone’s head, months or years before a letter of intent shows up.
A founder with three years of runway can treat these as manageable projects. A founder with three months is negotiating from behind before the process even starts.
Have you ever sat across from a buyer’s team and watched them ask about a line item you had not thought about in years? Most founders who have been through even a partial diligence process know that moment.
A strategic buyer and a financial buyer will weight things differently, since one cares more about how your customers overlap with theirs and the other cares more about how predictable your cash flow is, but the underlying questions both ask are remarkably similar.
Quality of Earnings analysis is usually where the real test begins. Independent accountants go through a company’s reported earnings and adjust for anything that reflects the owner’s life instead of the business’s ongoing operations.
Around DFW, that often includes suite tickets or season packages at AT&T Stadium or Globe Life Field, a country club membership out in Highland Park or Westlake, or a personal vehicle running through the company books. None of that is a problem on its own. It becomes one when it is not documented as a clean add-back and a buyer’s team has to go find it themselves.
The harder thing to see from the inside is owner dependence: how much of the business actually runs through one person’s judgment and relationships.
Businesses built on transferable operational systems—with documented processes and a management layer that can operate without the founder in the room—tend to command a meaningfully different multiple than businesses where every decision funnels through the top.
The workarounds that create this dependence usually did not start as a problem. They started as the fastest way to get something done fifteen years ago, and they simply never got revisited.
Harvard Business School’s overview of company valuation methods points to something founders often miss: a buyer is not really pricing your balance sheet—they are pricing the cash flows they expect your business to generate after they own it.
That is why GAAP-compliant financials matter, why a working capital peg needs to reflect reality instead of convenience, and why data room preparation ahead of an M&A process saves weeks once a deal is actually moving. Forbes’ guidance on preparing a business’s finances for sale makes a similar point: clean records move a deal faster, and rushing the process tends to cost the seller money.
Founders who leave this work until the letter of intent stage often end up negotiating from behind, sometimes settling for an earn-out provision that puts part of their payday at the mercy of performance they can no longer control.
A founder starting this process usually asks a fairly simple question first: Who is the right person to call? DFW has plenty of business brokers, sell-side advisory firms, and general consultants, and the distinctions between them are worth understanding before signing anything.
Most brokers and sell-side advisors get paid a success fee when a deal closes. That fee structure quietly favors closing something within 6–9 months at roughly today’s value, since a longer timeline delays payment without necessarily increasing it.
A founder sitting on a business that could be worth considerably more after a year or two of focused operational work often never hears that option from someone whose paycheck depends on moving fast. It’s not that every broker works against their client. It’s simply the shape of the incentive, and it’s worth knowing about going in, before an engagement letter gets signed.
CPAs, M&A attorneys, and wealth managers around DFW see the pattern often enough to recognize it: a founder calls a broker, gets a number based on where the business sits today, and only realizes later that a year of operational work might have changed that number considerably.
An operating partner works from a different starting point. An operator sits inside the business alongside the existing team, closing the same gaps a buyer’s sell-side diligence readiness review would eventually surface anyway. The measure of success shifts from speed to fit, making sure the eventual deal actually reflects what the business can do, even if that takes longer to get there.
Buyers evaluate founder-led businesses against a fairly predictable checklist. Our post The 5 Things PE Firms Look for When Buying a Founder-Led Business goes deeper into what is actually on it, a good next stop before deciding which kind of help makes sense.
Lighthouse Value Partners operates as an embedded partner for founder-led businesses across North Texas, usually stepping in long before any deal is on the table.
Take one DFW manufacturer LVP worked with. The founder had built the business over three decades, and virtually every major relationship in it (customers, vendors, key operational calls) ran through him personally. Revenue was solid. Margins were healthy. But he knew—in the way founders usually do—that the business could not run without him standing in the middle of it, and he had not had the room to fix that while also running the company day to day.
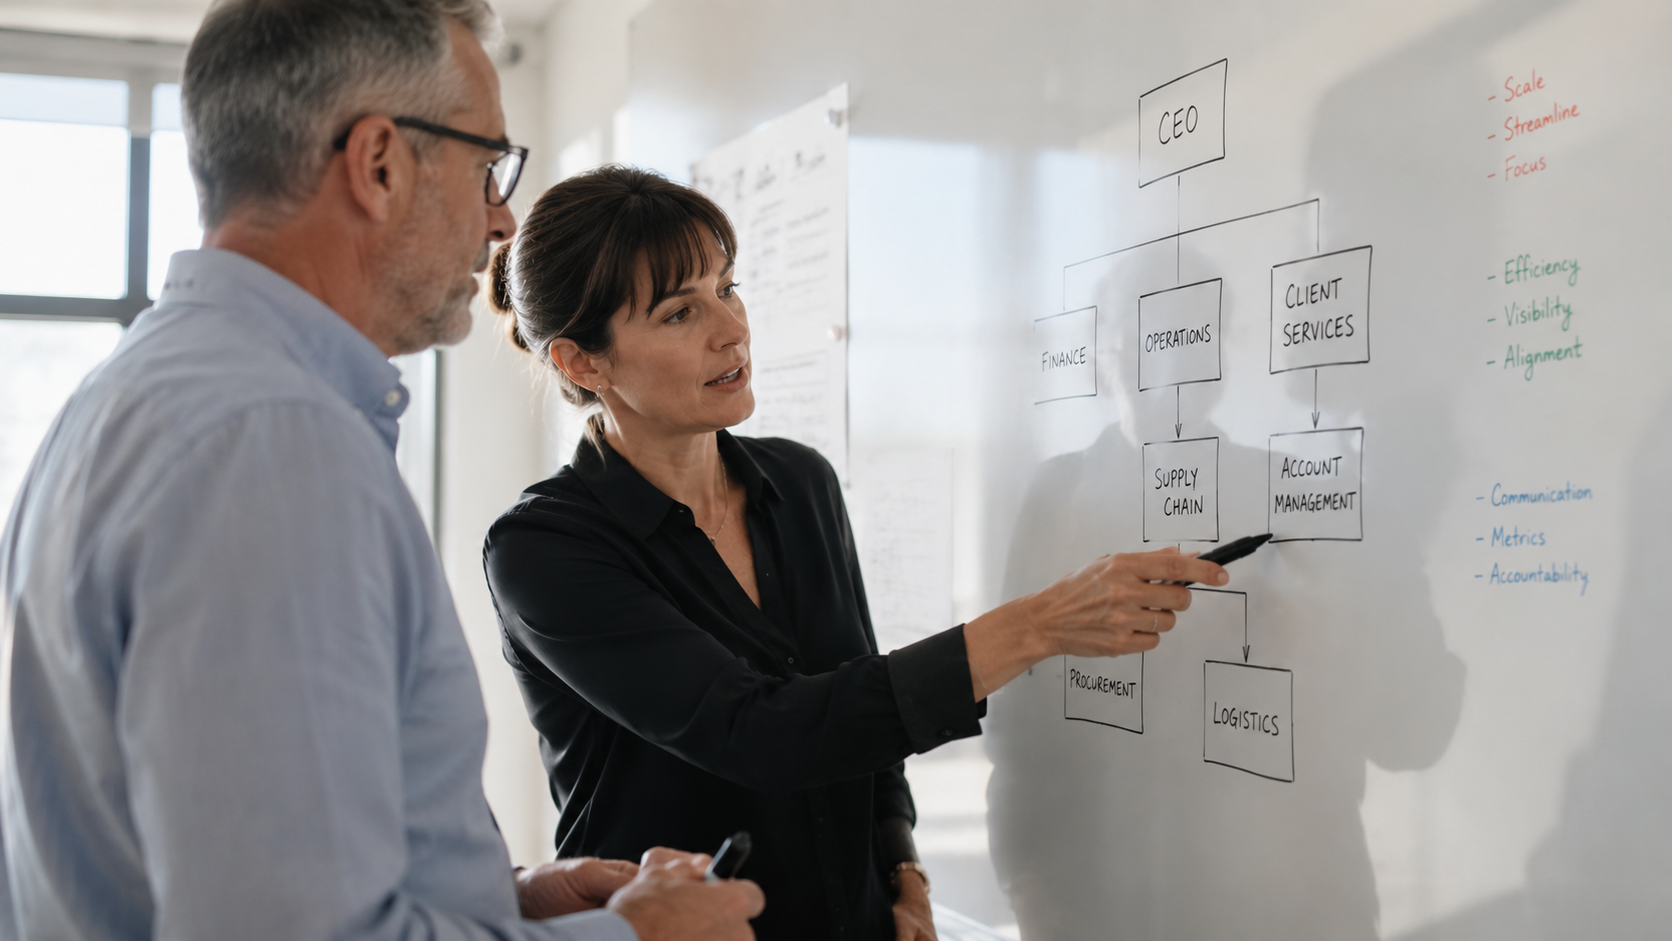
Closing that gap is the work: not stepping in to override the founder’s judgment, but building enough operational depth around him that the business can eventually stand—and sell—on its own.
That work runs through LVP’s Transaction Readiness Assessment (TRA), a scored evaluation that measures a business against what a buyer will genuinely test in diligence: financial reporting, owner dependence, customer concentration, documentation.
When a business needs sell-side advisory relationships, an executive hire, or a financial cleanup, LVP’s partners handle it directly, in-house. Profitable is not the same as transferable, and closing that particular gap usually takes longer than one meeting with a broker suggests.
None of the following requires a letter of intent already on the table. A few places a founder can start:
None of this requires deciding to sell. It builds a business capable of commanding a maximum exit multiple DFW buyers will genuinely pay, on a timeline the founder actually sets. For a lot of owners, that groundwork protects something larger than the transaction itself: legacy wealth creation Dallas founders hope to pass down usually depends less on the exact moment a business sells than on how ready it was when the right buyer finally showed up.
So what does that mean for a DFW founder who is still a few years out? Most owners in that position already have some sense of the distance between where the business sits today and where it needs to be for a premium multiple. They simply have not had the room to close it while also running the company day to day.
Profitable and transferable are not the same thing, and the businesses that land the strongest DFW exits are almost always the ones that started closing that gap early and on their own terms, not the ones scrambling once a buyer is already in the room asking questions.
For founders who want an honest look at where their business stands today, LVP’s Transaction Readiness Assessment is a reasonable place to begin.